The Checklist Before the Story: How an Expected-Evidence List Turns an Acquisition Thesis Into a Count of What Is Missing
Management tells a compelling acquisition story, but you have no fixed list of what proof should accompany it; this post shows how deciding the checklist first makes the gaps countable.
When management describes an acquisition as a success, most analysts judge the story by how it feels. Is the tone confident? Are the numbers vaguely supportive? Does the integration narrative hang together? That approach has a structural weakness: you can only react to what was said. You cannot easily notice what was never said.
LacunaIndex handles this by writing the checklist before reading the story. For each kind of management narrative, the platform keeps a fixed list of the evidence a careful outside reader should expect to find on the public record. The report then asks, item by item, whether that evidence is actually there.
One list per kind of story
The list lives in a single catalog in the codebase (the "expected evidence library"). It covers eight narrative types: artificial intelligence monetization, acquisition synergies, platform scale, efficiency, customer growth, capital allocation, vertical expansion, and international expansion. Each type has its own short, closed list of expected items, plus a one-paragraph rationale for why those items matter.
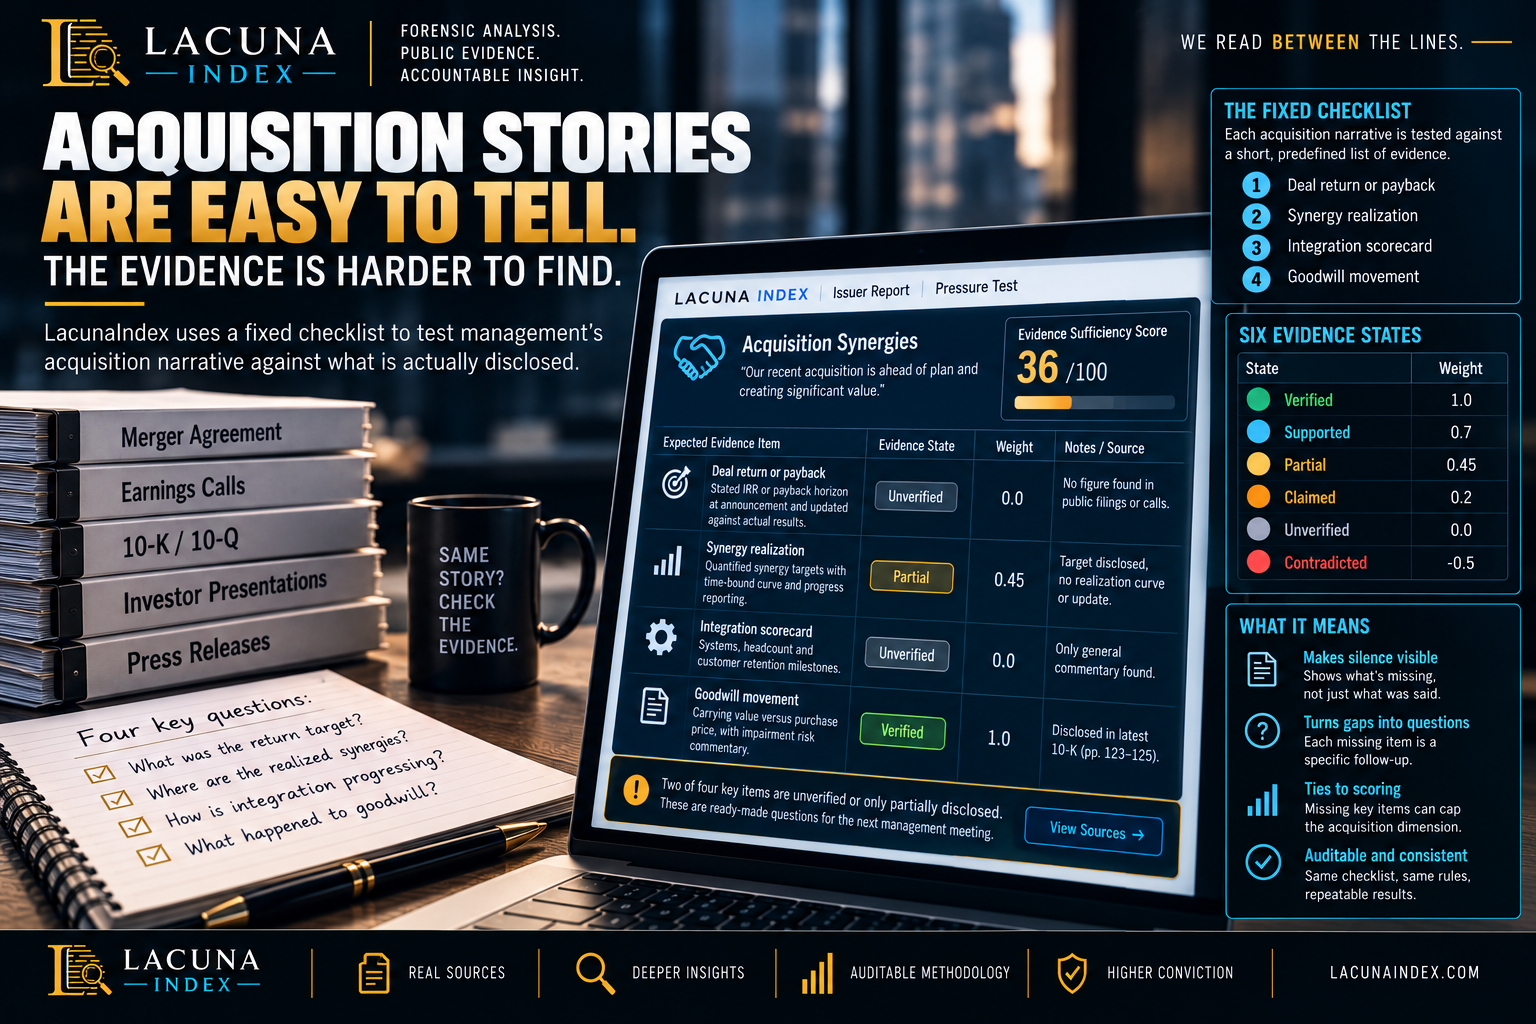
Take acquisition synergies. The rationale reads, in essence: acquisition theses are commitments, so the market should be able to trace promised synergies to realized outcomes year by year. The four expected items are:
- Deal return or payback. A stated internal rate of return (the annualized return the deal is meant to earn) or payback horizon, given at announcement and restated against actual results at later anniversaries.
- Synergy realization. Quantified cost or revenue synergy targets, with a time-bound curve and progress reporting.
- Integration scorecard. Public milestones such as systems cut-over, headcount harmonization and customer retention, tracked across reporting periods.
- Goodwill movement. The carrying value of goodwill (the premium paid over the identifiable assets) versus the purchase price, with commentary on the risk of write-down, normally found in the annual report filed with the Securities and Exchange Commission.
Each item also records where it would normally appear: annual filing, quarterly filing, proxy statement, investor day, earnings call, press release, or third-party source. That matters because a figure in a filing is stronger evidence than the same figure in a press release.
Six states, and a number for each
Every expected item is then classified into one of six evidence states. The states describe whether the public record supports the claim, not whether the claim is true. "Unverified" means nothing was found either way.
| State | What it means | Weight |
|---|---|---|
| Verified | Explicit, measurable disclosure directly substantiates the claim | 1.0 |
| Supported | Indirect operational evidence makes the claim credible without proving it | 0.7 |
| Partial | Disclosure exists but is incomplete | 0.45 |
| Claimed | An assertion with no measurable proof | 0.2 |
| Unverified | No public evidence found | 0.0 |
| Contradicted | Public evidence conflicts with the claim | -0.5 |
The weights are fixed in code, so two analysts looking at the same sources should land on the same state for the same item.
What the count looks like
The sufficiency score is the average of the item weights, scaled to 0 to 100 and clamped so it cannot fall below zero. Any item left unclassified is treated as unverified.
Here is an illustrative case (invented numbers, not a real issuer). A company says its largest acquisition is "ahead of plan." Reading the record against the four-item list:
- Deal return: no figure disclosed at announcement or since. Unverified (0.0).
- Synergy realization: a headline target was disclosed, but there is no realization curve or update. Partial (0.45).
- Integration scorecard: nothing beyond general commentary. Unverified (0.0).
- Goodwill movement: the filing shows the carrying value and discusses impairment risk. Verified (1.0).
The weights sum to 1.45 across four items, so the sufficiency score is 36 out of 100. More useful than the number is the second output: a list of the items that are unverified or merely claimed. Here that is the deal return and the integration scorecard. Those are your follow-up questions for the next call with management.
Why a fixed list changes the diligence conversation
It makes silence visible. A story with three strong anecdotes and no deal-return disclosure reads well. Against a four-item list, it shows two blanks.
It separates "weak" from "absent." Partial and claimed are different from unverified. The first two tell you management said something that fell short of proof. The last tells you nothing was found. Those call for different questions.
It ties gaps to scoring. Some expected items are linked to a score ceiling. If the deal return, synergy realization or integration scorecard is missing or only claimed, the "acquisition definition" dimension is capped. A thin record cannot be outweighed by good prose elsewhere.
It can be audited. Because the list is a catalog and not a mood, you can disagree with a specific item, such as whether goodwill commentary should count, and say exactly which line you would change.
Limits worth stating
- The catalog is a fixed, finite list. A narrative type that is not catalogued returns nothing rather than a guess.
- A high sufficiency score means the record is well documented, not that the strategy is good. A well-disclosed failure scores well on sufficiency.
- The state is a judgement on evidence in the sources reviewed. Evidence outside those sources is not counted.
- The synergy example above is hypothetical and is meant only to show the arithmetic.
A practical way to use it
Before your next management meeting on an acquisitive company, write down the four items above and mark each one verified, partial or missing from the filings alone. The gaps are your agenda. If management closes them with specifics, that is information. If the answers come back as adjectives, that is information too.